
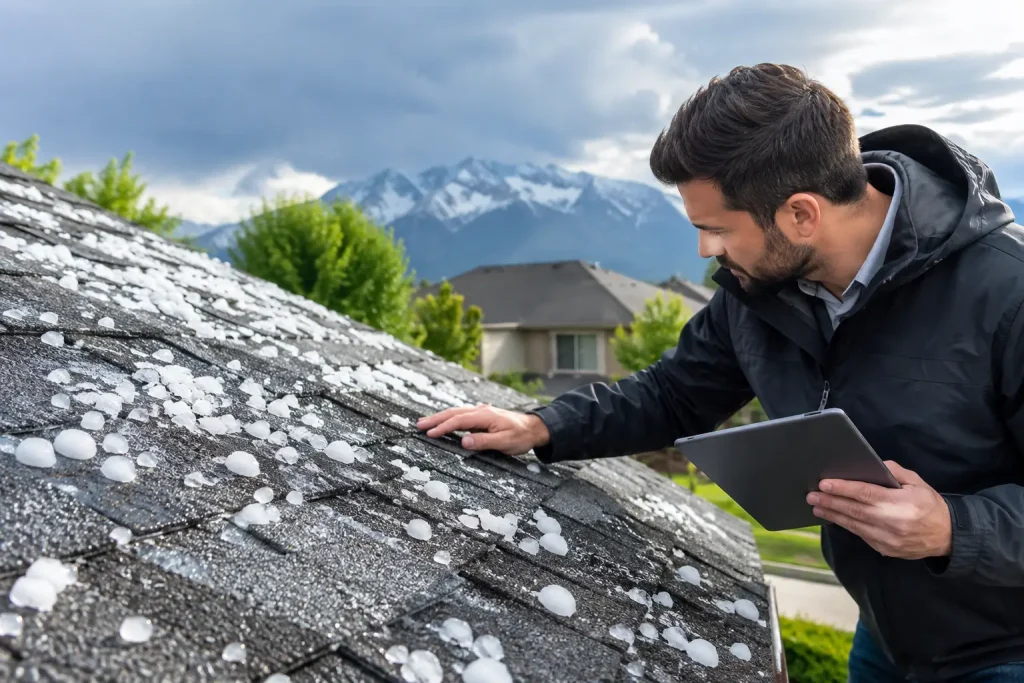
A hailstorm can leave behind more than a noisy afternoon. Even when your roof looks fine from the driveway, hail can bruise shingles, loosen protective granules, dent flashing, and create weak points that lead to leaks later. Knowing how to file a hail claim promptly can help protect your home, your budget, and your ability to get needed repairs completed before the next storm arrives.
The goal is not to rush into a roof replacement or assume every mark is covered. It is to document the damage carefully, understand what your policy requires, and give your insurance company the information it needs to evaluate your claim fairly.
Start With Safety and Prevent Further Damage
After a storm, do not climb onto your roof to look for hail damage. Wet surfaces, loose shingles, and hidden damage can make a roof unsafe. Start from the ground. Look for obvious signs such as shingles in the yard, dented gutters or downspouts, damaged siding, broken skylights, and hail marks on outdoor equipment.
If water is entering your home, take reasonable steps to limit additional damage. Place a bucket under active leaks, move furniture and electronics away from the area, and cover belongings with plastic sheeting if needed. If a temporary roof covering is necessary, save all invoices and receipts. Most policies require homeowners to prevent avoidable additional damage after a loss.
Do not make permanent repairs before your insurer has a chance to inspect the property unless an emergency repair is needed to keep the home secure. Temporary protection is usually appropriate. Replacing an entire roof before the claim is reviewed can make the process more complicated.
Get a Professional Roof Inspection
Hail damage is not always easy to spot. A trained roofing professional can identify issues that are difficult to see from the ground, including fractured shingle mats, granule loss, damaged ridge caps, punctured vents, and dents in soft metal components.
A professional inspection also helps separate storm-related damage from normal aging, installation issues, or wear that may not be covered by insurance. That distinction matters. Filing a claim without confirmed storm damage can create unnecessary frustration, especially if the claim is denied.
Ask for clear documentation of what was found. Photos, notes about the affected roof slopes, and a written description of the damage can be useful when you speak with your insurer. Big West Roofing provides free inspections for Utah homeowners who want an experienced assessment before moving forward.
Review Your Policy Before You File a Hail Claim
Take a few minutes to review your homeowners insurance policy or call your insurance agent with questions. You want to understand your deductible, coverage type, and deadline for reporting storm damage.
Your deductible is the amount you pay out of pocket before insurance coverage applies. For example, if your approved repair cost is $15,000 and your deductible is $2,000, the insurance payment may be $13,000, subject to your policy terms. In some cases, the cost of repairs may be close to or below the deductible, making a claim less practical.
Also check whether your roof is covered on a replacement cost value basis or an actual cash value basis. Replacement cost value generally pays the cost to replace covered materials, minus your deductible. Actual cash value accounts for depreciation, which may leave you responsible for a larger portion of the work on an older roof.
Every policy is different, so do not rely on a neighbor’s claim experience. Ask your insurer directly about hail coverage, exclusions, depreciation, and any deadlines that apply to your specific policy.
How to File a Hail Claim With Your Insurance Company
Once you have documented likely hail damage and reviewed your policy, contact your insurance company to begin the claim. Most insurers allow you to file by phone, through an online account, or in a mobile app.
When reporting the loss, provide the date of the storm, your property address, and a straightforward description of what you observed. Stick to the facts. You can explain that a roofing inspection found signs consistent with hail damage, but avoid guessing at repair costs or promising details you cannot verify.
Your insurer will assign a claim number and may schedule an adjuster inspection. Write down the claim number, the adjuster’s contact information, and the date and time of every conversation. Keeping a simple record can prevent details from getting lost as the claim moves forward.
It is helpful to gather your documentation in one place before the adjuster visit. This may include:
- Photos and videos taken after the storm
- A copy of the roofing inspection report
- Receipts for emergency mitigation or temporary repairs
- Photos of interior water damage, if present
- Notes about the storm date and any communications with your insurer
Do not exaggerate damage or include unrelated issues in the claim. Accurate documentation protects you and helps the process move more efficiently.
Be Present for the Adjuster Inspection When Possible
If your schedule allows, be present when the adjuster visits. You do not need to be a roofing expert, but you can point out the areas of concern, provide your documentation, and ask what happens next.
Many homeowners also ask their roofing contractor to be available during the inspection. A contractor can identify damaged components and help ensure the adjuster sees the same areas documented during the initial inspection. The contractor’s role is to provide professional information about the roof and the needed work. Your insurance company makes the final coverage decision.
After the inspection, the adjuster may provide an estimate or send one later. Review it carefully. Insurance estimates often list the covered repairs, material quantities, labor costs, depreciation, deductible, and any initial payment amount. If something appears to be missing, such as gutter damage, flashing, or code-required items, ask questions before work begins.
Understand the Estimate Before Signing a Contract
An approved claim does not always mean the estimate covers every detail of the completed project on the first pass. If additional covered damage is discovered during repairs, your contractor may document it and submit a supplement request to the insurer. This is a normal part of some restoration projects, especially when damage is hidden beneath shingles or other materials.
Before signing a repair or replacement contract, make sure you understand the scope of work. Ask which roofing materials will be used, whether damaged gutters or siding are included, how long the job is expected to take, and what workmanship warranty is provided.
Be cautious of anyone who offers to waive or hide your deductible. Your deductible is your responsibility under your insurance policy, and attempts to work around it can create legal and financial problems. A trustworthy contractor will explain your options clearly, provide a detailed estimate, and help you make decisions without pressure.
What to Do If Your Hail Claim Is Denied or Underpaid
A denial is not always the end of the conversation. Ask your insurer for the reason in writing and compare it with the findings from your roofing inspection. Sometimes the issue is insufficient documentation, a missed area of damage, a policy limitation, or a disagreement about whether the damage was caused by hail.
You can request a reinspection or ask for clarification on the estimate. Provide additional photos, contractor documentation, or evidence of related storm damage to gutters, vents, siding, and other exterior components. Keep communication polite and organized. The clearer your information, the easier it is for the insurer to review it.
If your roof has urgent damage but coverage remains uncertain, ask a local contractor about repair options that protect the home while you work through the claim decision. Waiting too long can turn a manageable roofing issue into interior damage, mold concerns, or more expensive repairs.
Move Quickly, but Do Not Feel Pressured
Utah weather can be unpredictable, and hail damage may not show up as a leak until months later. Report suspected damage within the timeline required by your policy, schedule an inspection promptly, and keep good records from the start.
At the same time, take a breath before committing to major work. The right contractor will give you clear answers, respect your insurance process, and focus on protecting your home for the long term. A careful first call after the storm can make the rest of the process far less stressful.